Florida Amendment 3: 2027 Property Tax Changes Explained

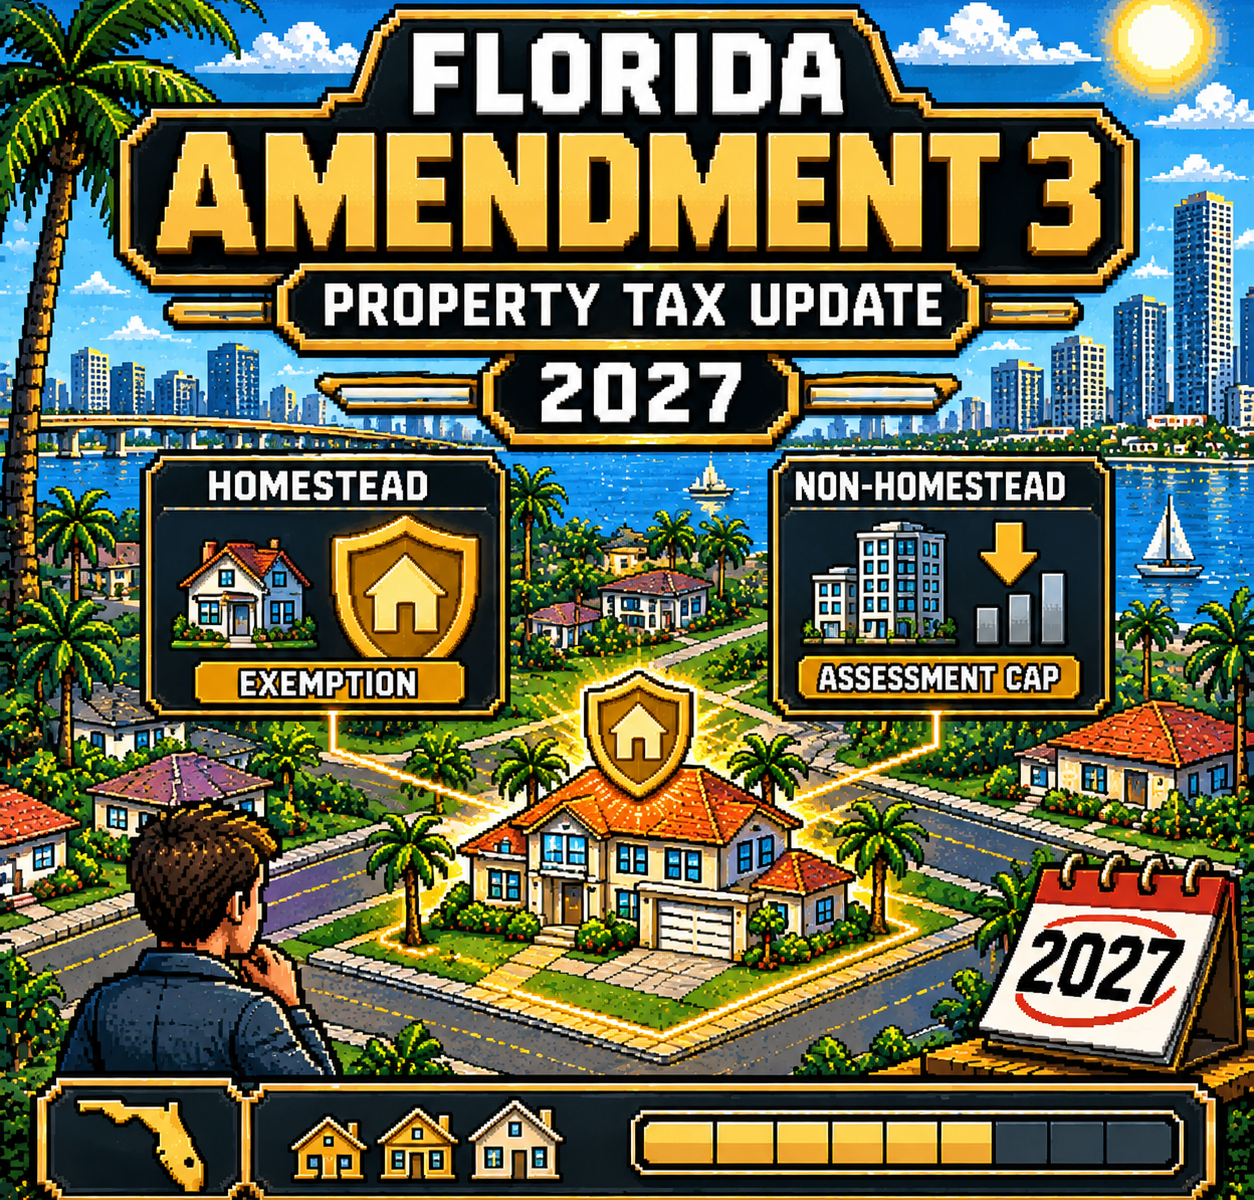
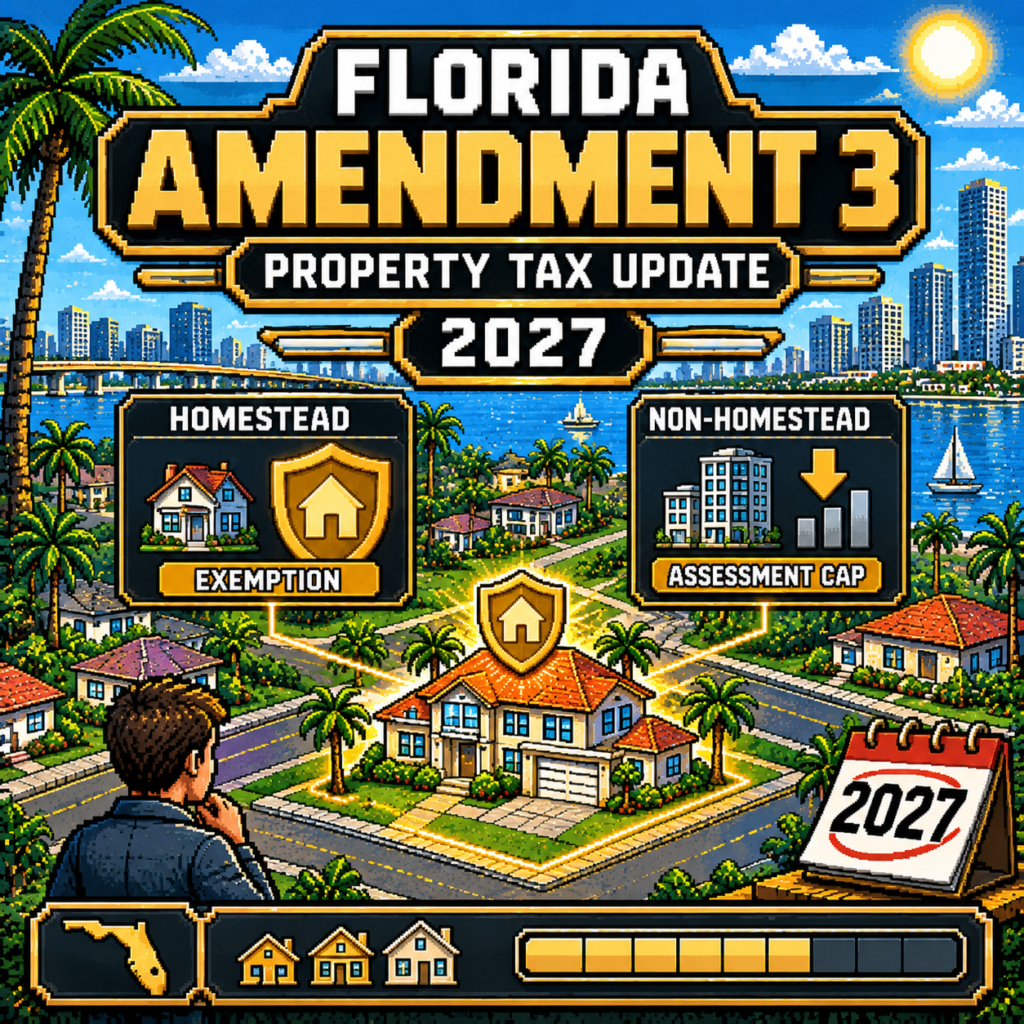
Florida Amendment 3: What Homeowners Need to Know About the 2027 Property Tax Changes

Managing homeownership costs in Florida involves balancing mortgage principal, interest, homeowners insurance, and local property taxes. In the November 3, 2026, general election, Florida voters approved Amendment 3, a constitutional amendment that alters the state’s property tax structure.

With significant voter support surpassing the 60% constitutional approval threshold, Amendment 3 introduces expanded homestead tax exemptions, lowers assessment caps on non-homestead real estate, and sets new guidelines for local tax revenues. Understanding these adjustments helps current homeowners, first-time buyers, and real estate investors evaluate future housing budgets accurately.

What Is Florida Amendment 3?

Florida Amendment 3 is a legislatively referred constitutional amendment passed by Florida voters on November 3, 2026. The measure required at least 60% voter approval to amend the Florida Constitution, a milestone it successfully cleared with nearly 62% of the vote.

The primary objective of Amendment 3 is to provide property tax relief by increasing the homestead exemption available to qualifying primary residences and reducing the annual assessed-value growth cap on non-homestead properties. It is important to note that Amendment 3 concerns property tax policy and should not be confused with previous state ballot measures. The provisions take effect on January 1, 2027.

What Property Tax Changes Does Amendment 3 Introduce?

Amendment 3 makes three principal modifications to Section 4 and Section 6 of Article VII of the Florida Constitution.

The New $150,000 Homestead Exemption in 2027

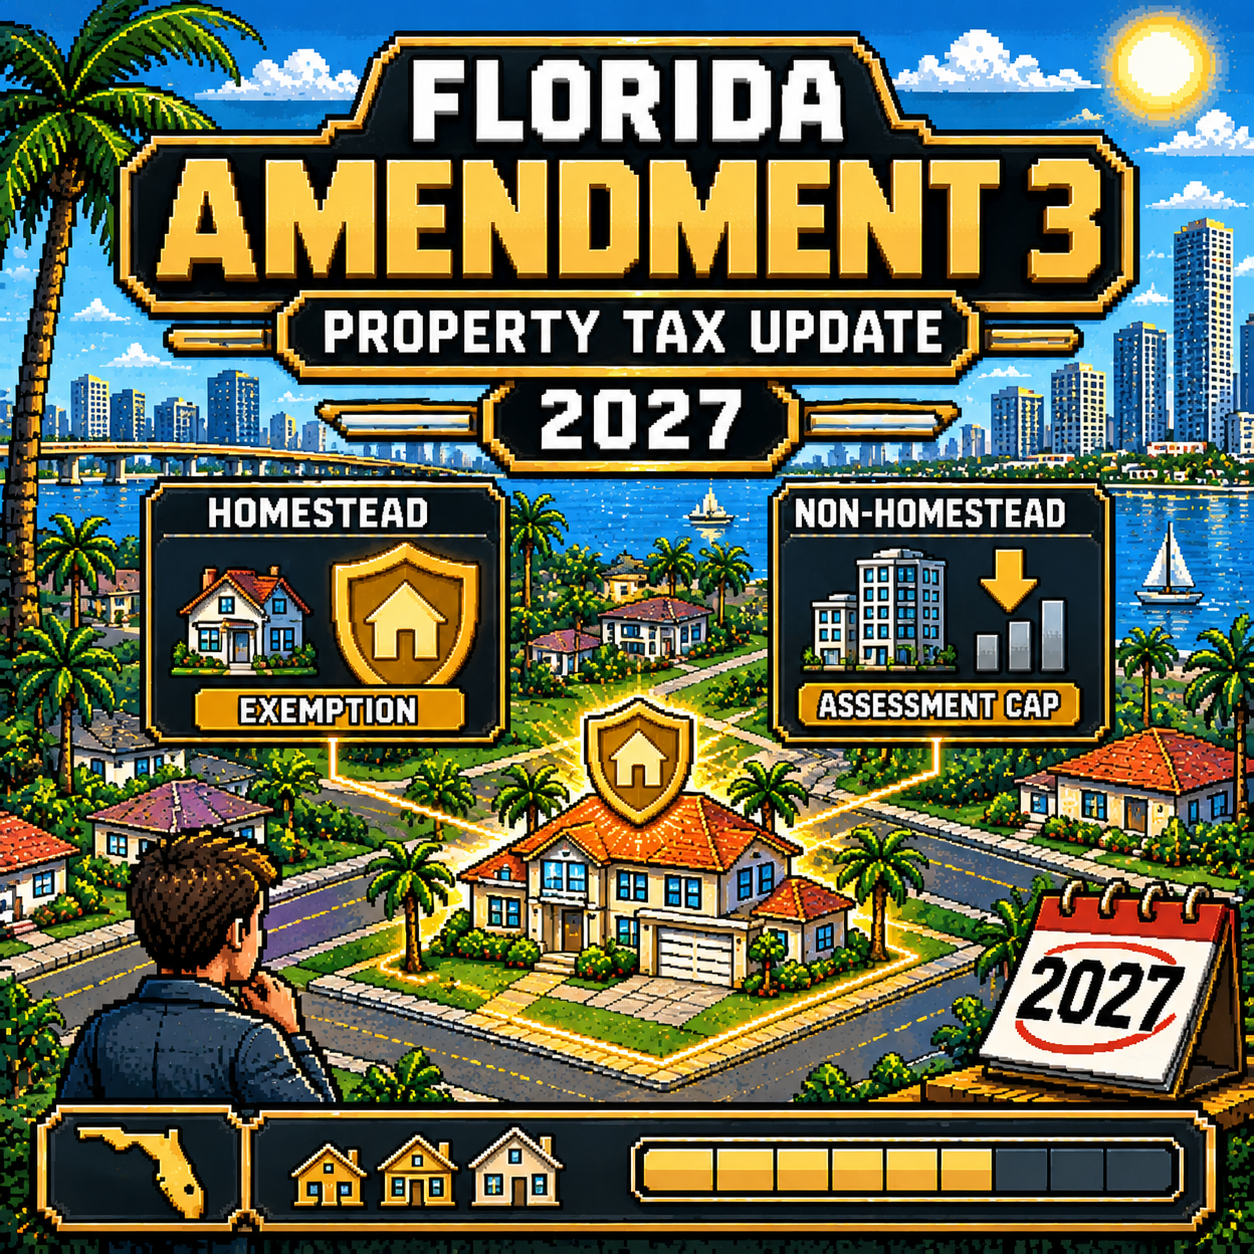
Beginning January 1, 2027, the homestead exemption for non-school property taxes increases to $150,000 of a qualifying primary residence’s assessed value.

Under prior law, Florida homeowners received up to $50,000 in homestead exemptions for non-school taxes ($25,000 for all levies, plus an additional $25,000 on assessed values between $50,000 and $75,000 for non-school levies). Amendment 3 expands this non-school shielding significantly. The existing $25,000 homestead exemption for school district taxes remains unchanged.

The $250,000 Homestead Exemption in 2028

On January 1, 2028, the non-school homestead exemption steps up again, shielding up to $250,000 of a qualifying home’s assessed value from non-school property taxes. Starting on January 1, 2029, this exemption amount will adjust annually for inflation based on changes in the Consumer Price Index (CPI).

The Reduction of the Non-Homestead Assessment Cap

For non-homestead properties—including rental properties, second homes, commercial real estate, and vacant land—Amendment 3 reduces the maximum annual assessment increase cap from 10% to 5% for non-school property taxes starting January 1, 2027.

This change limits how fast a property’s assessed value can rise year-over-year. However, a lower assessment growth cap does not guarantee a lower total property tax bill, as millage rates set by local taxing authorities and property improvements still affect the final tax calculation.

Who Qualifies for the Increased Homestead Exemption?

Not every property owner or newcomer receives the enhanced homestead exemption immediately:

    • Current Florida Residents: Individuals who establish and maintain legal Florida permanent residency on or before December 31, 2026, qualify for the expanded non-school homestead exemption when they establish their primary residence.

    • Five-Year Phase-In for New Residents: Individuals who establish permanent Florida residency after December 31, 2026, face a five-year waiting period before accessing the expanded non-school exemption. During these first five years, new residents receive the standard base homestead exemption. Starting in 2030, individual counties or municipalities may vote by a two-thirds majority to reduce this waiting period for critical local needs.

How Could Amendment 3 Affect Florida Homeowners and Homebuyers?

Property taxes are collected through county tax collectors and are directly integrated into monthly mortgage payments via escrow accounts. Understanding the relationship between tax exemptions and total housing costs is critical for budget planning.

What First-Time Homebuyers Should Consider

A property tax exemption shields a portion of a home’s assessed value from taxation, but it does not alter mortgage principal, interest rates, or loan qualification guidelines.

When buying a home, lenders calculate your debt-to-income (DTI) ratio based on the total monthly housing payment (principal, interest, taxes, and insurance). Because property tax bills on newly purchased homes reset based on the new just value (market price), buyers should work with lending professionals to model realistic post-closing tax obligations. Explore practical guidelines for calculating housing expenses in our guide to Mortgage Affordability and Homebuying Costs.

What Investors and Owners of Rental Properties Should Know

Because property taxes fund local government operations, county commissions, municipal governments, and special taxing districts face potential budget shifts. Legislative staff estimates indicated that expanding homestead exemptions could reduce local government tax revenues across Florida by several billion dollars annually as the $250,000 tier takes effect.

Local governments may adjust their millage rates, reallocate service budgets, or alter fee structures to maintain essential services such as emergency medical, fire, and infrastructure maintenance. As a result, exact tax savings will vary across Florida’s 67 counties based on local millage rate adjustments.

How Should Florida Buyers Prepare for the 2027 Changes?

    • Verify Your Residency Status: Ensure your primary residence records, driver’s license, and voter registration reflect Florida residency prior to December 31, 2026, if applicable.

    • Review County Property Appraiser Records: Check your home’s current assessed value and existing exemption status on your local property appraiser’s website.

    • Calculate Total Monthly Housing Costs: Account for post-sale reassessments when establishing a target purchase price. Learn how to prepare your finances with our resources on Mortgage Pre-Approval and Budget Planning.

    • Consult Qualified Professionals: Work with mortgage specialists and tax advisors to understand how upcoming tax changes impact your specific loan application and monthly escrow requirements.

Understand Your Mortgage Options with Level Mortgage

Navigating property tax updates, escrow requirements, and home financing requires a clear strategy. At Level Mortgage, we provide transparent guidance to help Florida buyers and homeowners make informed decisions about their home financing.

Contact Level Mortgage today to discuss your purchasing or refinancing goals with an experienced mortgage professional.

Read More

Let's Find the Right Mortgage for You!

Let's Find the Right Mortgage for You

A few quick questions so our team can understand your goals and follow up with options that fit.

Step 1 of 14
No credit check. No SSN required. Your information is sent securely. Level Mortgage LLC · NMLS #2703136 · Equal Housing Opportunity

About Us​

A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!

Follow Us

Location

United States

We do not share data with third parties for marketing/promotional purposes.

By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.

Copyright © 2025 Level Mortgage LLC | NMLS # 2703136 An Equal Housing Lender​

New 2027 FHFA Loan Limits: What Homebuyers Need to Know

New FHFA Loan Limits for 2027: What Borrowers Need to Know

Understanding how much you can borrow with a conventional mortgage is essential whether you are shopping for a new home or preparing to refinance an existing property. Every year, the Federal Housing Finance Agency sets conforming loan limits for mortgages acquired by Fannie Mae and Freddie Mac. These annual limits determine the boundary between a standard conventional mortgage and a jumbo loan, directly impacting interest rates, down payment requirements, and underwriting criteria.

As buyers and homeowners look ahead to late 2026 and 2027, staying informed about prospective limit adjustments helps ensure a smooth financing journey.

Have the 2027 FHFA Loan Limits Been Announced?

The official nationwide conforming loan limits for 2027 have not yet been published by the FHFA. By statute, the Federal Housing Finance Agency announces the upcoming year’s official baseline and high-cost area limits in late November each year, following the release of third-quarter home price index data.

Until the official announcement is released in late November 2026, the official baseline limit for a single-family home remains $832,750 for 2026. While industry estimates suggest limits could rise in 2027 based on quarter-over-quarter home price appreciation, borrowers should carefully distinguish between speculative projections, lender-specific early policies, and official government figures.

What Are the Current Conforming Loan Limits?

Until the 2027 official figures are formally established, the current 2026 limits serve as the active benchmark for government-sponsored enterprise backing. In 2026, the baseline limit for a single-family property increased by 3.26% over 2025.

Property Units2026 Baseline Limit (Standard Areas)2026 High-Cost Ceiling
1-Unit (Single-Family)$832,750$1,249,125
2-Unit (Duplex)$1,066,250$1,599,375
3-Unit (Triplex)$1,288,800$1,933,200
4-Unit (Fourplex)$1,601,750$2,402,625

Baseline Limits for One- to Four-Unit Properties

Conforming limits apply to residential properties containing one to four housing units. Multi-unit properties carry higher baseline caps to account for the additional purchase costs associated with multi-family real estate. Borrowers purchasing a duplex, triplex, or fourplex can access higher conforming financing amounts while utilizing standard conventional underwriting guidelines.

High-Cost Areas and County-Specific Limits

In areas where local median home values significantly exceed the baseline limit, the Housing and Economic Recovery Act sets higher local limits. These high-cost ceilings scale up to 150% of the baseline limit. County-specific adjustments ensure that buyers in high-cost real estate markets can secure conforming financing without immediately needing a jumbo mortgage.

How Does the FHFA Determine Annual Loan Limits?

The FHFA calculates annual conforming loan limits using its expanded-data House Price Index. The percentage adjustment measures the change in average single-family house prices between the third quarter of the prior year and the third quarter of the current year.

When national house prices rise, the conforming limit increases proportionally for the following calendar year. If national house prices drop, statutory rules prevent the conforming limit from decreasing; instead, the limit remains flat until house prices recover to previous peak levels. For detailed technical methodology, view the official FHFA Conforming Loan Limit Framework.

How Could the 2027 Limits Affect Homebuyers?

Interest Rates

When loan limits increase, buyers gain expanded access to conventional financing at higher purchase prices. This provides clear advantages compared to non-conforming or jumbo loans:

    • Simpler Qualifying Guidelines: Conforming mortgages generally require lower reserve balances and offer flexible credit requirements compared to jumbo loans.

    • Lower Down Payment Options: Buyers can obtain conventional financing with down payments as low as 3% to 5%, whereas jumbo loans often require 10% to 20% down.

    • Competitive Interest Rates: Conforming loans frequently carry lower interest rates and reduced fee structures compared to non-conforming options.

Higher limits do not automatically grant approval for a larger mortgage. Every borrower must still satisfy income, debt-to-income ratio, asset, and credit score guidelines during pre-approval. Learn how your financial profile impacts eligibility in our guide on Conventional Mortgage Qualification Rules.

What Borrowers in Florida Should Check

Florida borrowers should note that while most Florida counties adhere to the national baseline limit, certain high-cost areas feature elevated ceilings based on local property values. Checking your specific county limits is critical when structuring your offer. Read more on our page detailing Florida Mortgage Services and Local Programs.

What If a Lender Is Already Offering Higher Limits for 2027?

In the months preceding the official November announcement, some mortgage lenders introduce temporary early loan-limit policies. Under these programs, lenders allow borrowers to lock in loans slightly above current official limits in anticipation of the upcoming adjustment.

While early policies offer flexibility, borrowers must recognize that these represent individual lender programs rather than official federal policy. Early limits may carry specific delivery timelines, pricing adjustments, or restricted loan structures. Comparing options through an experienced advisor ensures you select the right financing path.

How Can Borrowers Prepare for the 2027 Announcement?

If you plan to purchase or refinance a property in late 2026 or early 2027, take these proactive steps:

    1. Review Your Budget: Determine a comfortable monthly payment rather than relying solely on the maximum loan limit.

    2. Organize Documentation: Gather tax returns, W-2s, and bank statements to streamline underwriting.

    3. Check Credit Health: Review your credit report to resolve errors and optimize your scoring profile. Explore our resources on Credit Scores and Debt-to-Income Preparation.

    4. Consult a Loan Officer: Review market expectations and evaluate whether a conforming, jumbo, or hybrid loan structure best fits your goals.

Talk to Level Mortgage About Your Mortgage Options

Navigating mortgage limits and choosing between conforming and jumbo financing requires personalized expertise. At Level Mortgage, we help buyers and homeowners understand their options, navigate changing regulations, and secure competitive financing structures. Contact Level Mortgage today to discuss your prospective purchase or refinance plans with a dedicated lending professional.

Read More

Leave Your Information Now!

Want personalized assistance? Visit our 'Contact Us' tab and leave your information with one of our experts.

Your Name(Required)
Your Email Address(Required)

About Us​

A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!

Follow Us

Location

United States

We do not share data with third parties for marketing/promotional purposes.

By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.

Copyright © 2025 Level Mortgage LLC | NMLS # 2703136 An Equal Housing Lender​

Why Buyers are Returning to the 2026 Housing Market

Is 2026 Your Year? Why Buyers Are Returning to the Housing Market

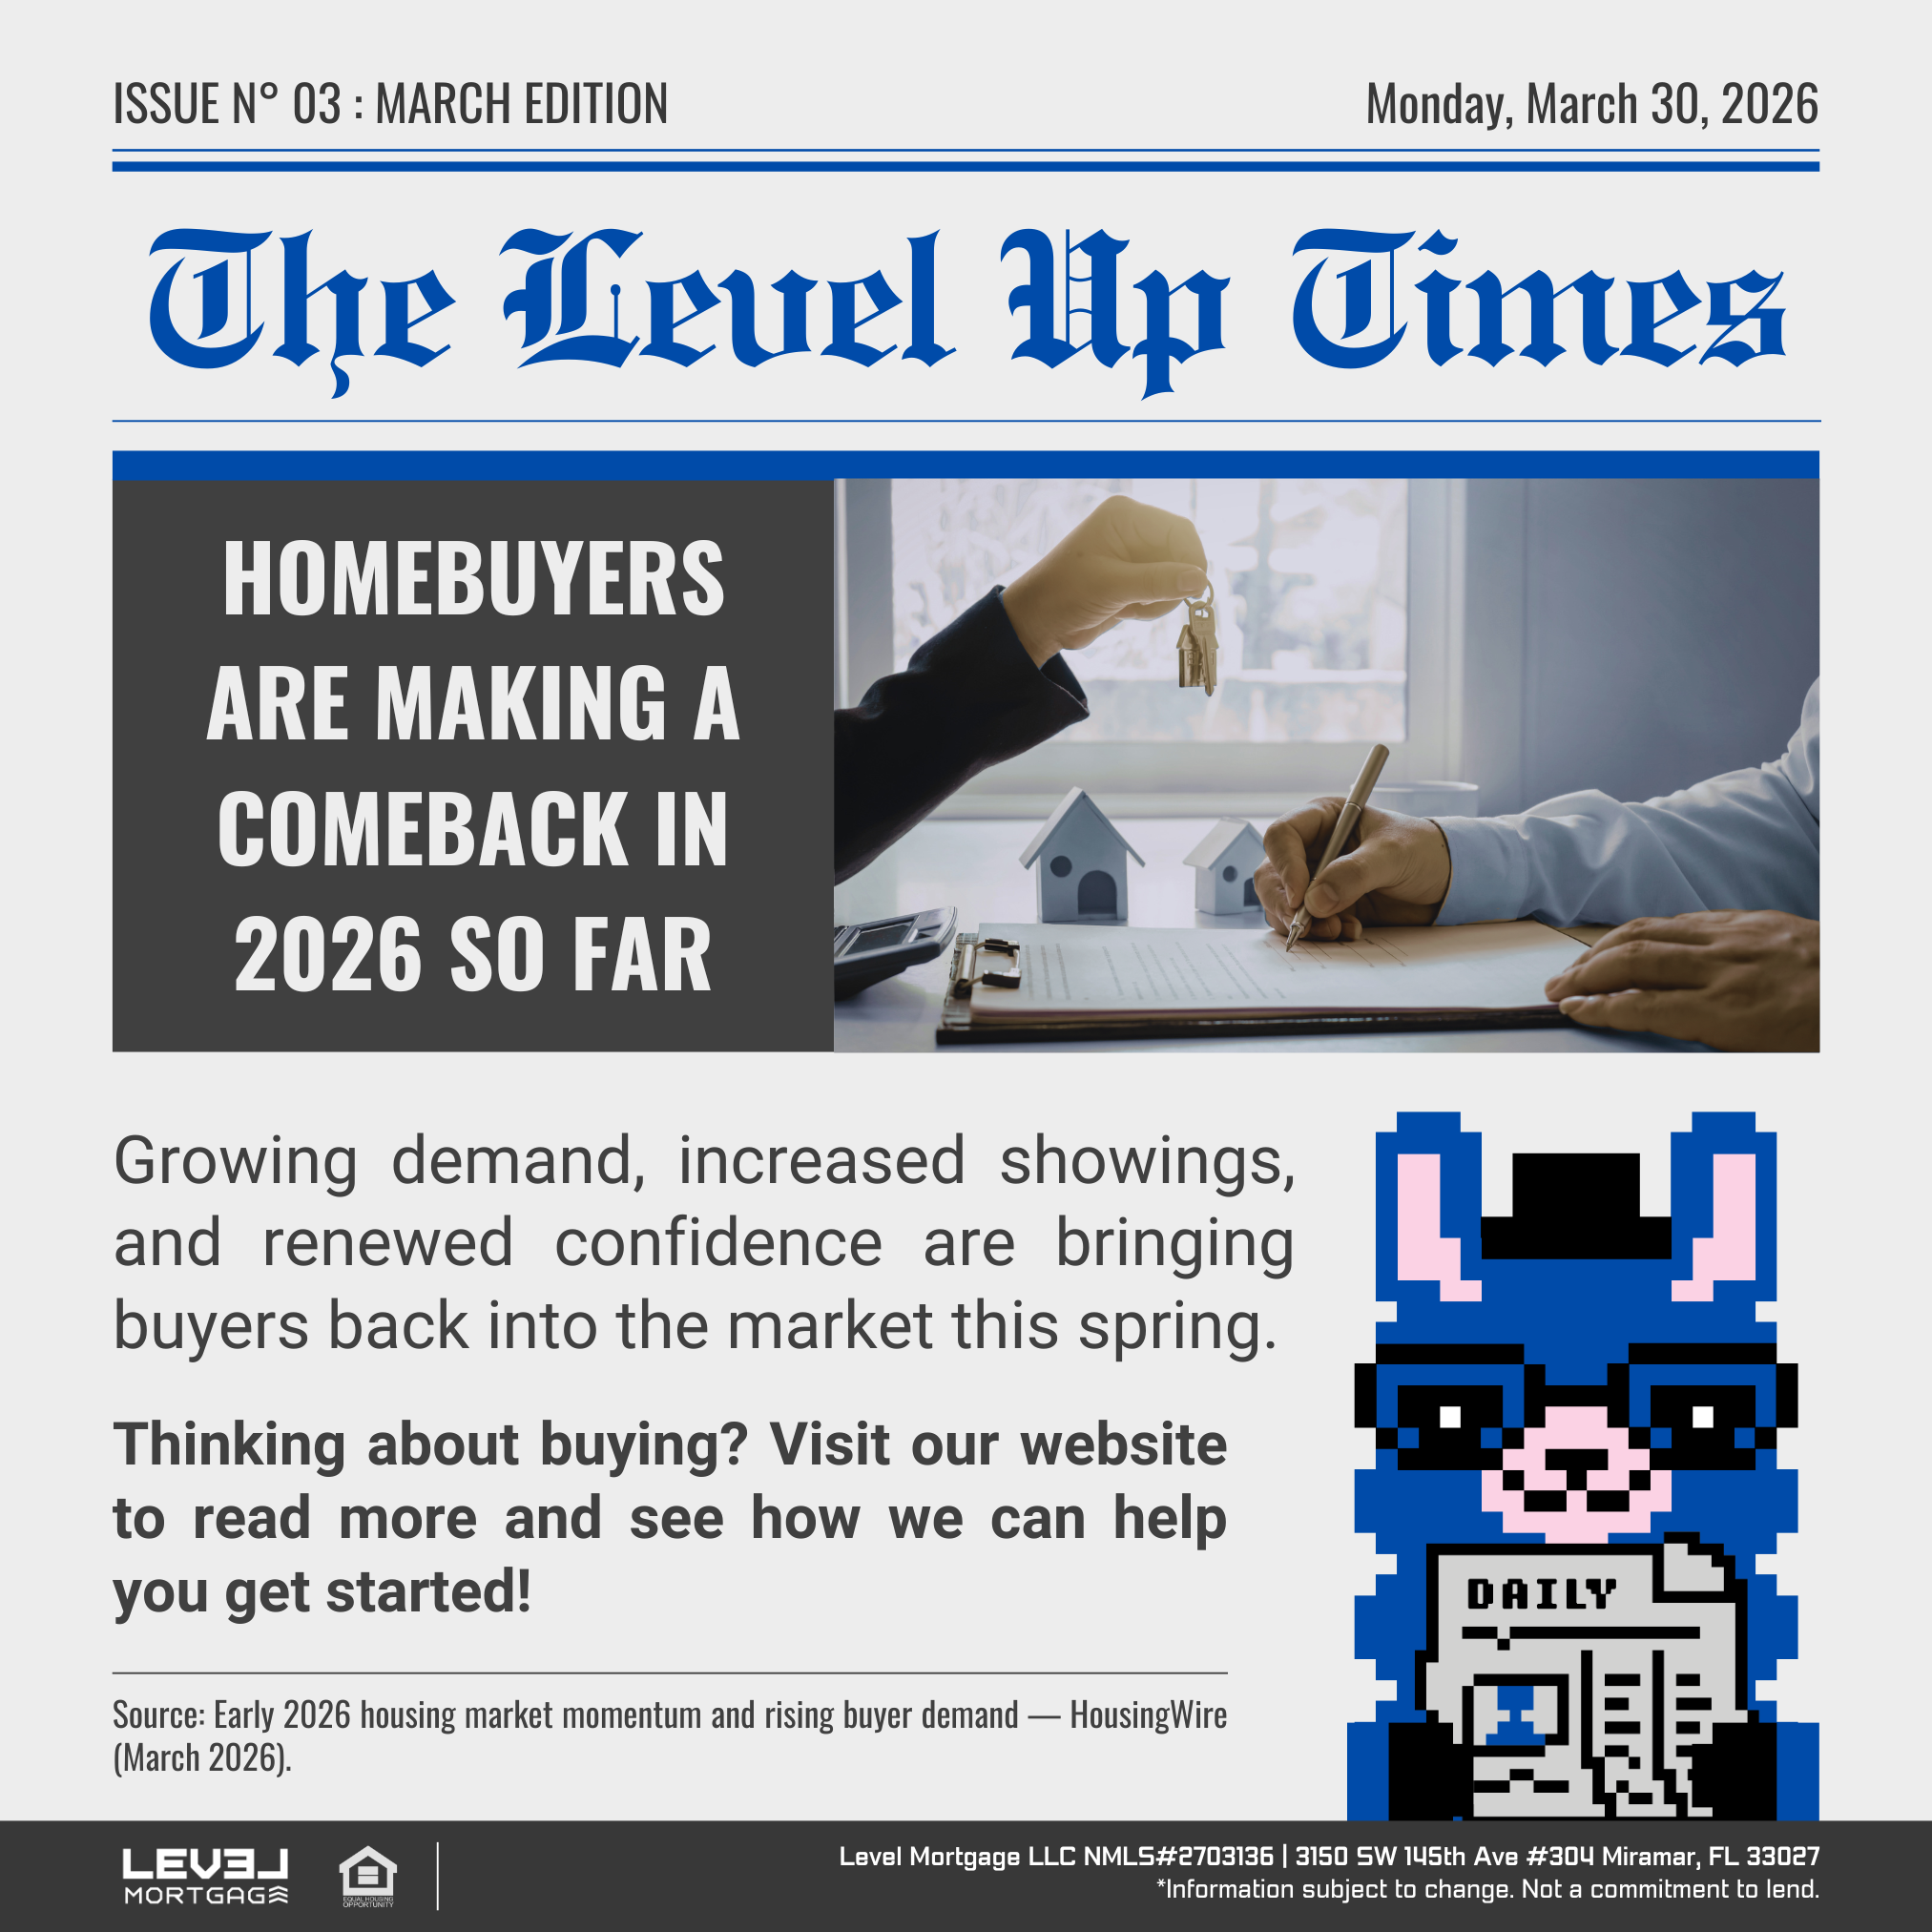
The “wait-and-see” approach that defined much of the last two years is officially shifting. As we move through 2026, the housing market is vibrating with a renewed energy that hasn’t been felt in seasons. For many who paused their homeownership dreams due to volatile rates or inventory shortages, the current landscape offers a compelling reason to take a second look.

At Level Mortgage, we believe clarity is the foundation of confidence. Understanding the data behind this shift is the first step in determining if 2026 is the right time for your next move.

The 2026 Housing Market Is Gaining Momentum

After several years of “rate lock” paralysis—where both buyers and sellers felt stuck in place—the market has entered a period of healthy recalibration. We are no longer seeing the frantic, unsustainable spikes of the early 2020s, nor the stagnant lows of the post-inflationary correction.

Instead, 2026 is characterized by intentionality. Buyers are re-entering the market not out of panic, but because the fundamentals of homeownership—stability, equity, and lifestyle—are outweighing the desire to “time the market.”

Signs Buyers Are Coming Back

The numbers tell a clear story of a market in motion. According to recent data and seasonal reporting, the “sideline” is getting a lot thinner.

    • Rising Mortgage Applications: The Mortgage Bankers Association (MBA) recently reported a 14% year-over-year increase in purchase applications. This indicates that a significant wave of buyers is moving from the “browsing” phase into the “financing” phase.

    • Increased Home Showings: Real-time data from Redfin shows that home tours and requests for showings are up 11% nationwide compared to this time last year.

    • Spring Activity Surge: While the spring season always brings a boost, 2026 has seen the earliest start to the “buying season” in five years, as buyers attempt to get ahead of the traditional summer rush.

What’s Driving Buyer Confidence in 2026

Why now? The return of the buyer isn’t accidental; it is driven by three specific economic shifts that have created a more predictable environment.

1. Stabilizing Home Prices

The National Association of Realtors (NAR) indicates that while home values continue to appreciate, the pace has moderated to a sustainable 3% to 4% annually. This predictable growth allows buyers to plan their finances without the fear of a sudden 20% price hike while they save.

2. Increased Inventory

A major hurdle in previous years was the “Inventory Desert.” However, Fannie Mae reports that active listings have increased by 18% as more homeowners decide to trade up or downsize, finally feeling comfortable leaving their pandemic-era low rates.

3. Adaptation to the Interest Rate Environment

Buyers have largely accepted the “new normal.” With the Federal Reserve maintaining a more consistent stance, mortgage rates have stabilized around the 5.8% to 6.2% range. This stability has replaced the “rate shock” of 2023 and 2024 with a sense of predictability.

What This Means for You as a Buyer

If you are a first-time buyer or someone who paused your search in 2024, the current conditions offer a unique window of opportunity.

    • Less “Bidding War” Fatigue: While demand is up, the increase in inventory means you are less likely to face 20 competing offers on a single property. You have more room to breathe and perform due diligence.

    • The Cost of Waiting: With prices continuing to rise steadily, waiting for a “perfect” rate that may never return could cost you more in lost equity than you would save on a monthly payment.

    • Strategic Mindset: In 2026, the “best” deal isn’t just about the lowest price; it’s about the right total cost of homeownership, including your loan structure and long-term equity goals.

Why Your Mortgage Strategy Matters More Than Ever

In a more active market, your financing is your strongest negotiation tool. Sellers in 2026 are looking for “sure bets”—buyers who have their financing fully vetted and ready to go.

A mortgage is not a one-size-fits-all product. Depending on your goals, a Custom Loan Strategy might include:

    • Exploring adjustable-rate options if you plan to move in five years.

    • Utilizing specialized programs for first-time buyers.

    • Structuring your down payment to maximize your monthly cash flow.

Navigating these choices requires more than an online calculator; it requires a partner who understands the nuances of the 2026 economy.

How Level Mortgage Helps You Move Forward with Confidence

At Level Mortgage, we don’t just process loans; we provide a roadmap. We know that the 2026 housing market can feel complex, but it doesn’t have to be overwhelming.

Our team is dedicated to providing the educational resources, market insights, and personalized guidance you need to make a decision that fits your life and your legacy. We act as your advocate, ensuring that when you find the right home, you have the right financing to back it up.

Ready to Explore Your Options?

The 2026 market is moving, and you should feel empowered to move with it. Whether you’re just starting to save or you’re ready to get pre-approved, we’re here to help you understand your affordability and find the best path forward.

Read More

Leave Your Information Now!

Want personalized assistance? Visit our 'Contact Us' tab and leave your information with one of our experts.

Your Name(Required)
Your Email Address(Required)

About Us​

A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!

Follow Us

Location

United States

We do not share data with third parties for marketing/promotional purposes.

By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.

Copyright © 2025 Level Mortgage LLC | NMLS # 2703136 An Equal Housing Lender​

Federal Reserve Cuts Rates Again: Why Florida Real Estate Buyers Should Act Now

Federal Reserve Cuts Rates Again: Why Florida Real Estate Buyers Should Act Now

The Federal Reserve cut interest rates again in December 2025, lowering the federal funds rate to 3.5%–3.75%, its third consecutive cut this year. This move is designed to stimulate borrowing amid a cooling labor market and persistent inflation. For Florida real estate buyers and investors, this represents a prime opportunity to lock in lower mortgage rates, expand portfolios, and capitalize on rising housing demand.

The Fed’s Decision: A Third Consecutive Rate Cut

On December 10, 2025, the Federal Reserve announced a quarter-point cut to its benchmark federal funds rate, bringing it down to 3.5%–3.75%. This marks the third rate cut since September, signaling the Fed’s commitment to supporting economic growth despite lingering inflation concerns.

Impact on Mortgage Rates

Mortgage rates, which had surged to their highest levels since 2000 just two years ago, have gradually declined throughout 2025. Following the Fed’s December cut:

  • 30-year fixed mortgage rates are trending downward, offering relief to buyers who faced affordability challenges in 2023–2024.

  • Refinancing opportunities are expanding, allowing homeowners to reduce monthly payments and free up cash flow.

  • Short-term borrowing costs (home equity lines, adjustable-rate mortgages) are directly impacted, becoming more attractive.

Florida Real Estate Market Outlook

Florida’s housing market is uniquely positioned to benefit from lower rates due to strong demand drivers:

  • Population Growth: Florida added over 300,000 new residents in 2025, driven by migration from high-cost states.

  • Inventory Constraints: Housing supply remains tight, keeping upward pressure on prices.

  • Investment Hotspots: Cities like Miami, Tampa, and Orlando continue to attract domestic and international investors.

Statistics:

  • Florida median home price: $410,000 in November 2025, up 6% year-over-year.

  • Rental demand: Vacancy rates below 5% statewide, with Miami at 3.2%.

  • Mortgage applications: Increased 12% month-over-month following the Fed’s September cut, signaling strong buyer response.

Why This Is a Great Opportunity

For Buyers:
  • Lower Monthly Payments: A 0.25% drop in mortgage rates can save buyers $50–$100 per month on a $400,000 loan.

  • Improved Affordability: More households qualify for financing, expanding the buyer pool.

  • Timing Advantage: Acting before potential rate hikes in 2026 ensures locking in favorable terms.

For Investors:
  • Cheaper Leverage: Lower borrowing costs improve ROI on rental properties and flips.

  • Rising Demand: Florida’s demographic trends ensure strong rental yields and appreciation.

  • Portfolio Expansion: Investors can refinance existing properties to free capital for new acquisitions.


Conclusion

The Fed’s December 2025 rate cut is a strategic move to stabilize the economy, but for Florida real estate buyers and investors, it’s more than just monetary policy — it’s a doorway to opportunity. With mortgage rates trending lower, housing demand strong, and Florida’s growth trajectory intact, now is the time to act. Buyers can secure affordable financing, while investors can leverage cheaper capital to expand portfolios in one of the nation’s hottest real estate markets.


Read More

Leave Your Information Now!

Want personalized assistance? Visit our 'Contact Us' tab and leave your information with one of our experts.

Your Name(Required)
Your Email Address(Required)

About Us​

A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!

Follow Us

Location

United States

We do not share data with third parties for marketing/promotional purposes.

By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.

Copyright © 2025 Level Mortgage LLC | NMLS # 2703136 An Equal Housing Lender​