Home Buying Advantages for Federal Employees in Florida
Purchasing a home is a major milestone, and for public servants working within the federal government, navigating the housing market requires a clear understanding of financial strengths and available loan structures. Whether you are stationed in Miami, Orlando, Tampa, Jacksonville, or Tallahassee, Florida offers a dynamic real estate landscape. Understanding how your career intersects with mortgage underwriting can open doors to competitive financing and valuable assistance programs.
Do Federal Employees Get Special Mortgage Benefits?
A common misconception is that federal civilian employment automatically unlocks a proprietary mortgage product designed exclusively for government workers. In reality, federal employment does not create a standalone civilian mortgage program. Instead, federal employees benefit from stable employment history, predictable income documentation, and full eligibility for standard and government-backed loan programs. Furthermore, depending on your specific job classification, veteran status, and location, you may qualify for state-level assistance initiatives or specialized public service programs.
Why Federal Employment Can Strengthen a Mortgage Application
When mortgage underwriters evaluate a file, they look closely at stability, capacity, and capital. Federal employment offers distinct advantages in these categories.
Consistent pay history and stable career structures make it easier for lenders to verify monthly income and project long-term repayment capacity. Documented earnings, regular step increases, and robust federal benefits contribute to a reliable financial profile. Additionally, while lenders do not expect borrowers to liquidate retirement accounts, having established assets and Thrift Savings Plan accounts can strengthen an overall financial picture.
Federal employees frequently experience relocations due to agency transfers, promotions, or new assignments. Managing a relocation involves weighing whether to sell an existing property, rent it out, or purchase a new primary residence in Florida. Evaluating these choices carefully ensures that your real estate decisions align with your broader financial goals.
Mortgage Options for Federal Employees in Florida
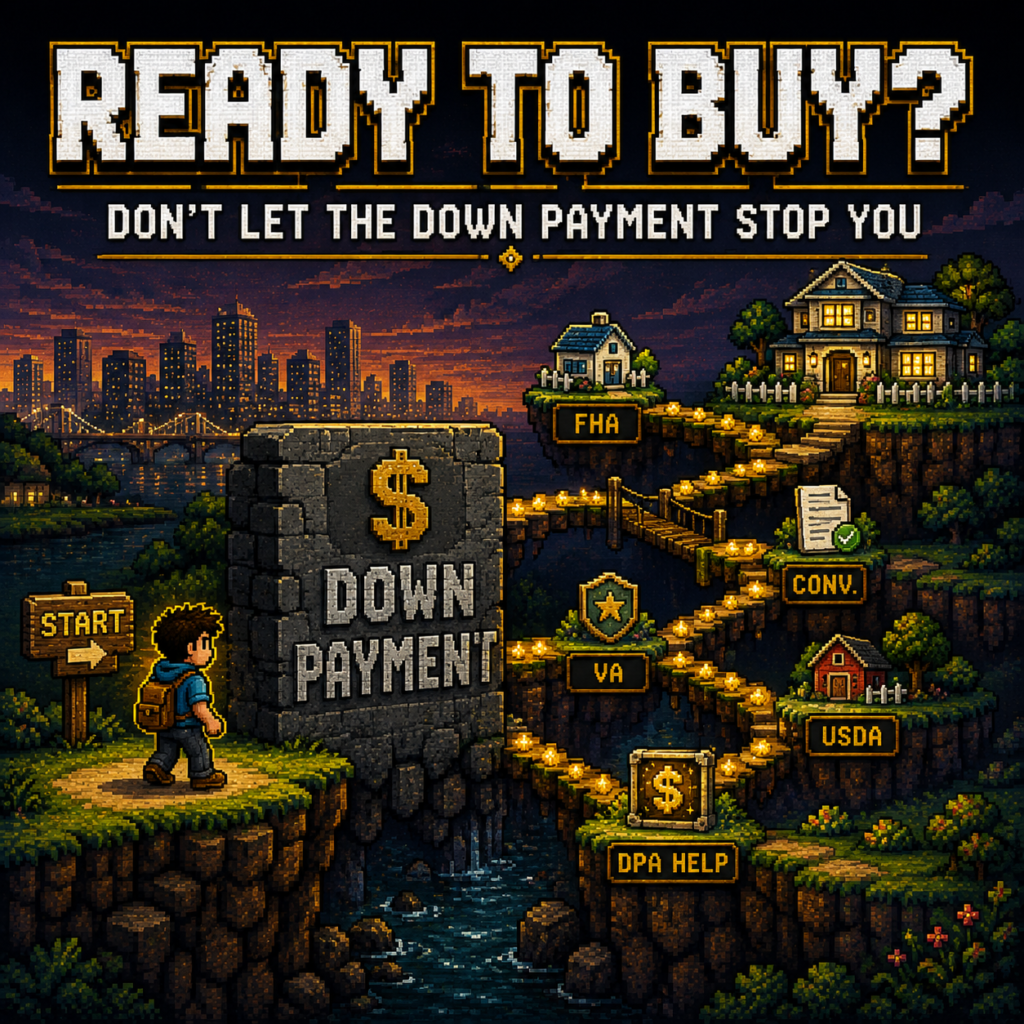
Federal workers can choose from several core financing options depending on their financial profile, down payment resources, and property location.
Conventional Loans
Conventional financing remains a popular choice for buyers with strong credit scores and established savings. These loans often feature competitive interest rates and flexible down payment options starting as low as three to five percent for qualified borrowers. Private mortgage insurance applies when putting down less than twenty percent, but it can be removed once sufficient equity is achieved.
FHA Loans
Backed by the Federal Housing Administration, FHA loans provide flexible credit guidelines and accessible down payment structures. Borrowers with a credit score of 580 or higher can qualify for a minimum down payment of 3.5 percent.For 2026, single-family FHA loan limits in Florida start at a baseline of $541,287 and scale higher in designated high-cost counties.
VA Loans
It is important to note that VA loans are not granted simply because someone works as a civilian federal employee. They are reserved for eligible veterans, active-duty servicemembers, and qualifying military personnel. For federal workers who also maintain military service backgrounds, VA financing offers exceptional benefits, including zero percent down payment requirements and the elimination of monthly private mortgage insurance.
USDA Loans
USDA loans offer zero percent down payment financing for eligible properties located in designated rural and suburban areas throughout Florida. Borrowers must meet specific household income limits and ensure the property meets geographic eligibility rules.
Can Federal Employees Qualify for Florida Hometown Heroes?
Many public sector workers wonder if they can access state assistance programs such as the Florida Hometown Heroes Program, managed through the Florida Housing Finance Corporation.While the program is open to a wide range of essential professions, eligibility is not universal for every federal worker.
To qualify under current guidelines, at least one occupying borrower must work full-time for a Florida-based employer and meet specific occupation criteria.Additionally, applicants must be first-time homebuyers who have not owned a primary residence in the past three years, unless exempt as a veteran or purchasing in a federally designated target area.Eligible participants can receive up to five percent of the first mortgage amount, capped at $35,000 with a $10,000 minimum, delivered as a zero percent interest, non-amortizing second Florida Down Payment Assistance program.
Other Programs Worth Exploring
Beyond state assistance, federal employees can explore standard mortgage products and regional grants. Lenders often pair conventional or government-backed loans with First-Time Homebuyer Programsto minimize upfront costs. While profession-based initiatives like Good Neighbor Next Door offer unique opportunities, they require strict adherence to specific job categories and designated revitalization areas rather than general federal employment status.
Documents Federal Employees Should Prepare
Gathering the right documentation early streamlines the Mortgage Pre-Approval process. Borrowers should prepare:
Government-issued identification
Recent pay stubs covering at least thirty days
W-2 forms from the past two years
Federal employment verification records, such as standard SF-50 forms where applicable
Bank statements for all asset and checking accounts
Federal tax returns if self-employed income or complex deductions apply
Mistakes to Avoid Before Applying
Navigating the mortgage market requires careful planning. Avoid assuming that federal employment guarantees instant approval without credit checks. Do not skip comparing multiple loan programs to find the best fit. Avoid making large credit purchases, opening new lines of credit, or changing jobs during the underwriting process, as these actions can disrupt your approval status. Always factor in ongoing costs like property taxes, homeowners insurance, and maintenance when determining your budget.
Final Thoughts
Purchasing a home in Florida is an exciting step, and federal employees possess strong employment credentials that appeal to lenders. By evaluating your financial position, comparing loan options, and working with an experienced mortgage strategist, you can navigate the market with confidence.
Take the next step in your homeownership journey. Connect with a qualified mortgage expert at Level Mortgage today to review your eligibility, compare loan programs, and explore available financing strategies tailored to your goals.
Want personalized assistance? Visit our 'Contact Us' tab and leave your information with one of our experts.
About Us
A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!
We do not share data with third parties for marketing/promotional purposes.
By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.