Managing homeownership costs in Florida involves balancing mortgage principal, interest, homeowners insurance, and local property taxes. In the November 3, 2026, general election, Florida voters approved Amendment 3, a constitutional amendment that alters the state’s property tax structure.
With significant voter support surpassing the 60% constitutional approval threshold, Amendment 3 introduces expanded homestead tax exemptions, lowers assessment caps on non-homestead real estate, and sets new guidelines for local tax revenues. Understanding these adjustments helps current homeowners, first-time buyers, and real estate investors evaluate future housing budgets accurately.
Florida Amendment 3 is a legislatively referred constitutional amendment passed by Florida voters on November 3, 2026. The measure required at least 60% voter approval to amend the Florida Constitution, a milestone it successfully cleared with nearly 62% of the vote.
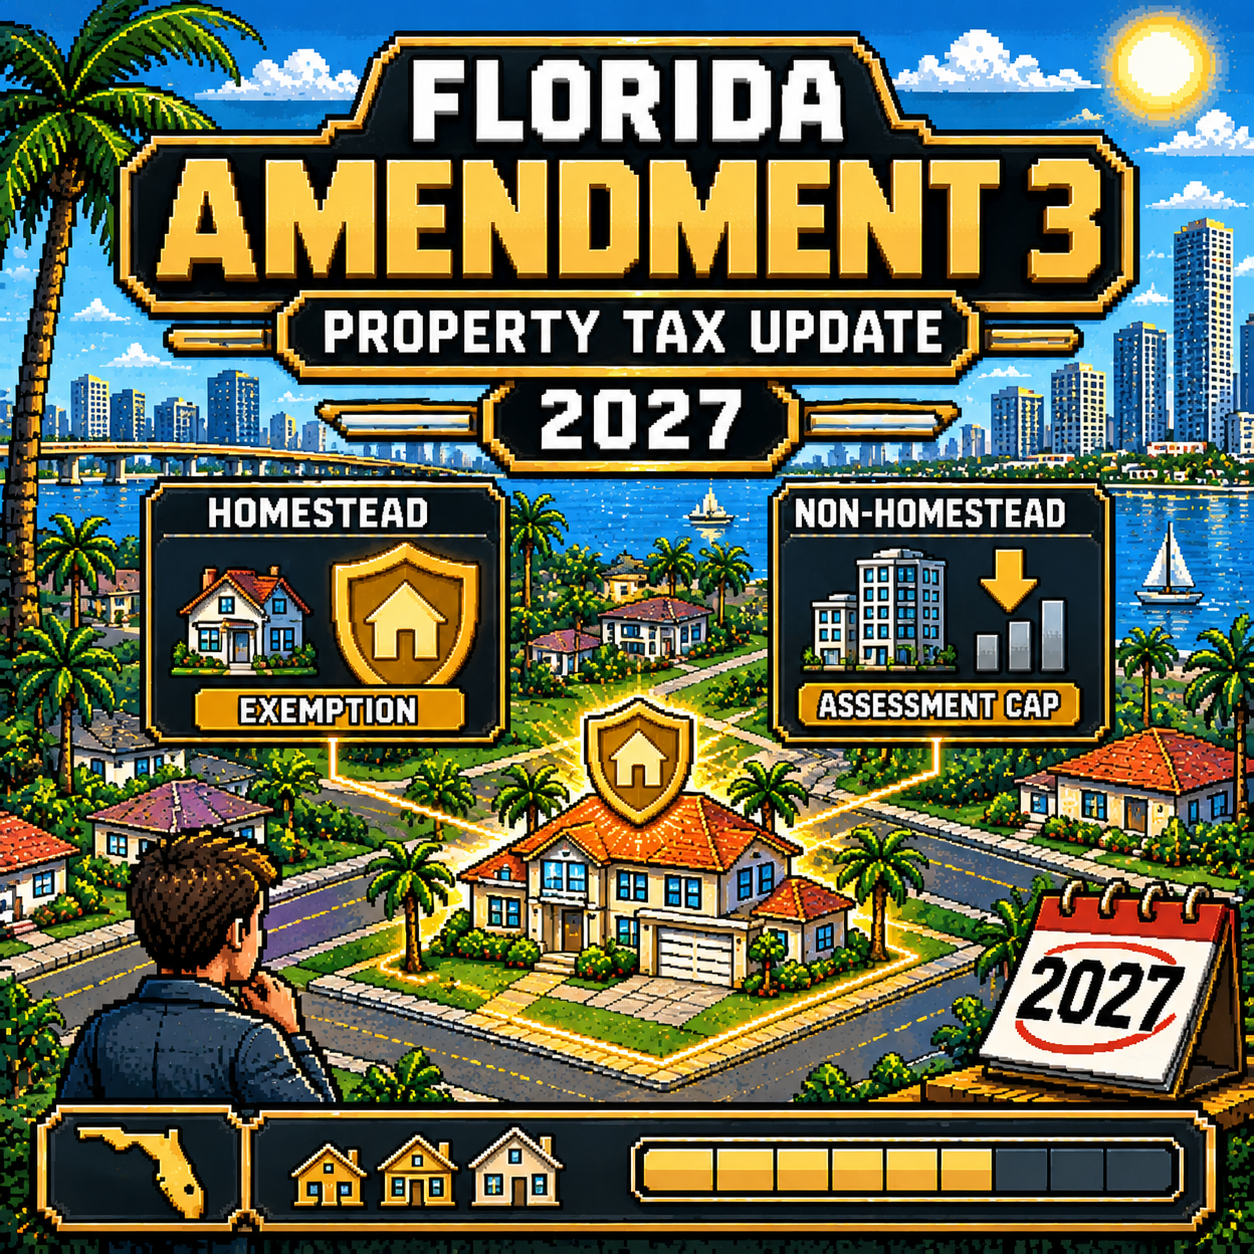
The primary objective of Amendment 3 is to provide property tax relief by increasing the homestead exemption available to qualifying primary residences and reducing the annual assessed-value growth cap on non-homestead properties. It is important to note that Amendment 3 concerns property tax policy and should not be confused with previous state ballot measures. The provisions take effect on January 1, 2027.
Amendment 3 makes three principal modifications to Section 4 and Section 6 of Article VII of the Florida Constitution.
Beginning January 1, 2027, the homestead exemption for non-school property taxes increases to $150,000 of a qualifying primary residence’s assessed value.
Under prior law, Florida homeowners received up to $50,000 in homestead exemptions for non-school taxes ($25,000 for all levies, plus an additional $25,000 on assessed values between $50,000 and $75,000 for non-school levies). Amendment 3 expands this non-school shielding significantly. The existing $25,000 homestead exemption for school district taxes remains unchanged.
On January 1, 2028, the non-school homestead exemption steps up again, shielding up to $250,000 of a qualifying home’s assessed value from non-school property taxes. Starting on January 1, 2029, this exemption amount will adjust annually for inflation based on changes in the Consumer Price Index (CPI).
For non-homestead properties—including rental properties, second homes, commercial real estate, and vacant land—Amendment 3 reduces the maximum annual assessment increase cap from 10% to 5% for non-school property taxes starting January 1, 2027.
This change limits how fast a property’s assessed value can rise year-over-year. However, a lower assessment growth cap does not guarantee a lower total property tax bill, as millage rates set by local taxing authorities and property improvements still affect the final tax calculation.
Not every property owner or newcomer receives the enhanced homestead exemption immediately:
Current Florida Residents: Individuals who establish and maintain legal Florida permanent residency on or before December 31, 2026, qualify for the expanded non-school homestead exemption when they establish their primary residence.
Five-Year Phase-In for New Residents: Individuals who establish permanent Florida residency after December 31, 2026, face a five-year waiting period before accessing the expanded non-school exemption. During these first five years, new residents receive the standard base homestead exemption. Starting in 2030, individual counties or municipalities may vote by a two-thirds majority to reduce this waiting period for critical local needs.
Property taxes are collected through county tax collectors and are directly integrated into monthly mortgage payments via escrow accounts. Understanding the relationship between tax exemptions and total housing costs is critical for budget planning.
A property tax exemption shields a portion of a home’s assessed value from taxation, but it does not alter mortgage principal, interest rates, or loan qualification guidelines.
When buying a home, lenders calculate your debt-to-income (DTI) ratio based on the total monthly housing payment (principal, interest, taxes, and insurance). Because property tax bills on newly purchased homes reset based on the new just value (market price), buyers should work with lending professionals to model realistic post-closing tax obligations. Explore practical guidelines for calculating housing expenses in our guide to Mortgage Affordability and Homebuying Costs.
Because property taxes fund local government operations, county commissions, municipal governments, and special taxing districts face potential budget shifts. Legislative staff estimates indicated that expanding homestead exemptions could reduce local government tax revenues across Florida by several billion dollars annually as the $250,000 tier takes effect.
Local governments may adjust their millage rates, reallocate service budgets, or alter fee structures to maintain essential services such as emergency medical, fire, and infrastructure maintenance. As a result, exact tax savings will vary across Florida’s 67 counties based on local millage rate adjustments.
Verify Your Residency Status: Ensure your primary residence records, driver’s license, and voter registration reflect Florida residency prior to December 31, 2026, if applicable.
Review County Property Appraiser Records: Check your home’s current assessed value and existing exemption status on your local property appraiser’s website.
Calculate Total Monthly Housing Costs: Account for post-sale reassessments when establishing a target purchase price. Learn how to prepare your finances with our resources on Mortgage Pre-Approval and Budget Planning.
Consult Qualified Professionals: Work with mortgage specialists and tax advisors to understand how upcoming tax changes impact your specific loan application and monthly escrow requirements.
Navigating property tax updates, escrow requirements, and home financing requires a clear strategy. At Level Mortgage, we provide transparent guidance to help Florida buyers and homeowners make informed decisions about their home financing.
Contact Level Mortgage today to discuss your purchasing or refinancing goals with an experienced mortgage professional.
A few quick questions so our team can understand your goals and follow up with options that fit.
United States
We do not share data with third parties for marketing/promotional purposes.
By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.
Copyright © 2025 Level Mortgage LLC | NMLS # 2703136 An Equal Housing Lender