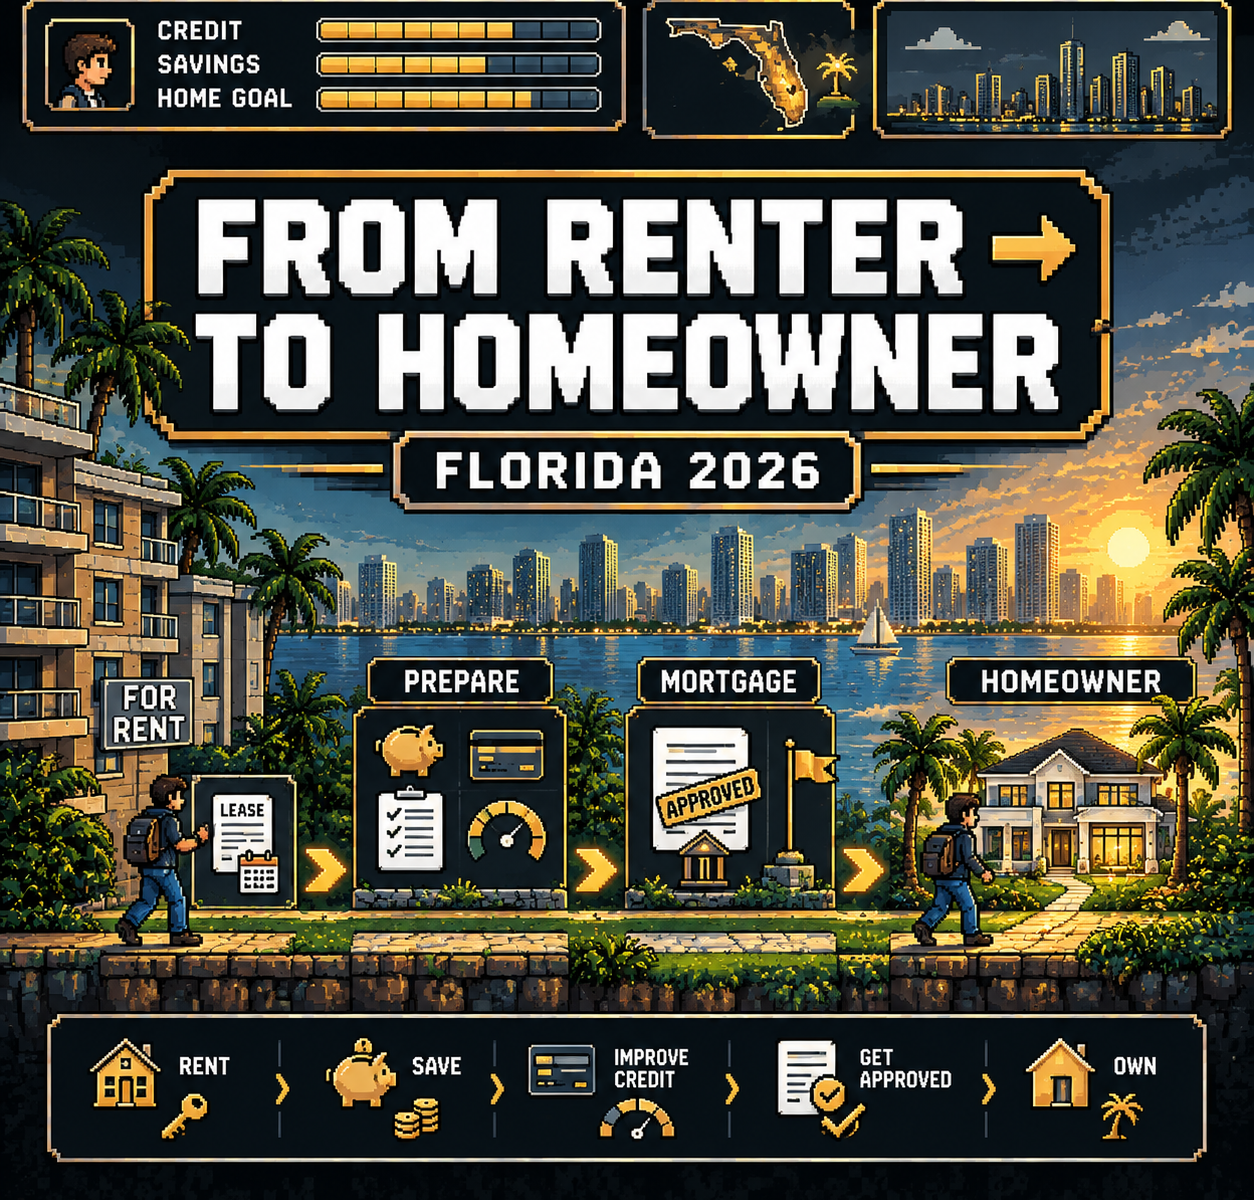
From Renter to Homeowner: Mastering the Lease Transition in Florida (2026)
Deciding whether to sign another lease or take the leap into homeownership is one of the most significant financial choices a renter can face. For many Florida residents, the arrival of a lease renewal notice serves as a natural checkpoint. Navigating this transition requires strategic timing, careful financial evaluation, and an understanding of current market dynamics. By preparing ahead of time, renters can position themselves to secure favorable financing and successfully step into homeownership.
When Should Renters Start Planning to Buy a Home?
Start Before Your Lease Renewal Date
Waiting until thirty days before your lease expires to think about buying a home is a recipe for unnecessary stress. Landlords typically require sixty to ninety days of notice before a lease ends. If you intend to transition from renting to owning, you should begin mapping out your strategy at least six months prior to your lease expiration date. This window gives you adequate time to review your credit profile, build necessary savings, and speak with a lending professional without feeling rushed by a looming moving deadline.
Why Timing Matters for Mortgage Preparation
Mortgage underwriting relies heavily on verified financial history. Lenders look for steady income, consistent employment records, and clean credit reports. Giving yourself a multi-month runway allows you to resolve minor credit report errors, pay down revolving balances, and optimize your debt-to-income ratio. Proper timing ensures that when you find the right property, your financial profile is completely mortgage-ready.
What Renters Need to Do Before Applying for a Mortgage
Review Your Credit
Your credit score directly influences the mortgage interest rate you receive. Most conventional loan programs require a minimum credit score of 620, while government-backed options like FHA loans may accept scores starting at 580 with a three and a half percent down payment. Reviewing your credit reports early allows you to address any inaccuracies and take steps to improve your standing before submitting formal loan applications.
Calculate Your Debt-to-Income Ratio
Mortgage lenders examine your debt-to-income ratio to determine how much housing payment you can comfortably manage. This ratio compares your monthly debt obligations, including car loans, student loans, and credit card minimums, to your gross monthly income. Keeping your debt-to-income ratio within acceptable lender thresholds is essential for successful first-time homebuyer mortgage options.
Build Your Down Payment and Closing-Cost Funds
Purchasing a home involves more than just a down payment. Buyers must also account for closing costs, which typically range from two to five percent of the purchase price. Accumulating a dedicated savings buffer well in advance ensures you are fully prepared for these upfront financial obligations.
Understanding the Florida Homebuying Market in 2026
Home Prices and Inventory
The Florida real estate landscape continues to experience a healthy rebalancing phase. Recent figures show that the median single-family home price in Florida hovers around $415,000, reflecting stable growth compared to previous years according to 2026 Florida housing market data. Meanwhile, housing inventory has adjusted, creating a more balanced environment where buyers have clearer opportunities to negotiate and find properties that align with their long-term goals.
Mortgage Rates and Affordability
Interest rates remain a central consideration for buyers navigating today’s economic climate. Average 30-year fixed mortgage rates hover near 6.95 percent, while 15-year fixed options average closer to 6.28 percent. Because mortgage rates directly impact monthly buying power, prospective homeowners should evaluate their budget carefully and explore various Florida mortgage programs to optimize their monthly payment structure.
From Rent Payment to Mortgage Payment
Transitioning renters often assume that moving from a $2,500 monthly rent payment means they can easily afford a $2,500 mortgage payment. However, a monthly mortgage payment comprises several distinct components. Beyond principal and interest, homeowners must budget for property taxes, homeowners insurance, private mortgage insurance if putting down less than twenty percent, and potential homeowners association or condominium fees. Evaluating the complete monthly housing cost ensures there are no surprises after closing.
Florida Programs That May Help First-Time Buyers
First-time buyers in the Sunshine State have access to several specialized support initiatives. For example, the Florida Hometown Heroes Program provides eligible full-time workers with up to $35,000 in down payment and closing cost assistance through a zero-interest, 30-year deferred second mortgage. Exploring these state and local resources with a knowledgeable professional can significantly reduce your upfront cash requirements.
Your Lease-to-Homeownership Timeline
A structured timeline keeps your transition organized:
Six to twelve months before lease expiration: Review credit reports, pay down revolving balances, build savings, and establish a realistic purchase budget.
Three to six months before lease expiration: Consult with a mortgage specialist, explore financing options, and secure mortgage pre-approval.
One to three months before lease expiration: Begin actively touring homes, coordinate your purchase closing date with your lease end, and finalize your loan documents.
Should You Renew Your Lease or Prepare to Buy?
Deciding between another year of renting and buying a home depends on a careful assessment of your personal circumstances. Evaluate how long you plan to stay in the area, your current savings, job stability, and local housing inventory. If you value long-term stability, building equity, and customizing your living space, preparing to buy is a compelling path forward.
Final Takeaway
Mastering the lease transition from renting to owning requires foresight, financial preparation, and expert guidance. By understanding your credit, evaluating total housing costs, and exploring available assistance programs, you can approach your lease expiration with confidence. To learn more about your financing options or to start your credit and mortgage preparation, contact LevelMTG today to speak with an experienced mortgage professional.
Want personalized assistance? Visit our 'Contact Us' tab and leave your information with one of our experts.
About Us
A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!
We do not share data with third parties for marketing/promotional purposes.
By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.