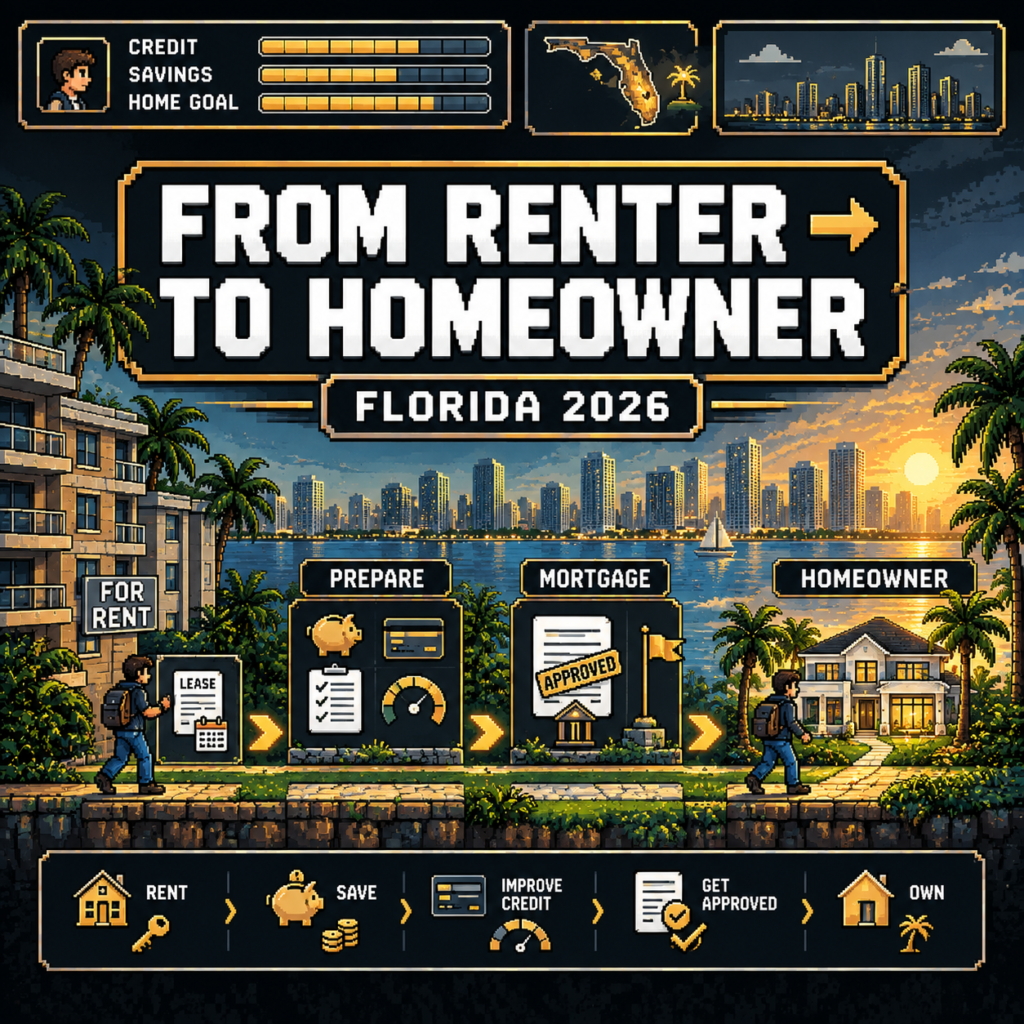
For many renters, the dream of homeownership often collides with the reality of saving for a down payment, managing credit scores, or navigating a competitive housing market. In the 2026 economic landscape, where home prices and interest rates remain key discussion points for prospective buyers, alternative paths to homeownership frequently attract attention. Among these alternatives is the lease option, commonly discussed under the broader umbrella of rent-to-own arrangements.
Before signing any agreement, it is essential to understand how lease options work, how they differ from traditional purchases, and whether they genuinely solve a financing challenge or simply postpone the mortgage qualification process.
What Is a Lease Option?
A lease option is a dual agreement consisting of a standard residential lease combined with an option contract. This structure gives the tenant the legal right, but not the obligation, to purchase the property at a predetermined price within a specified timeframe, usually one to three years.
Lease Option vs. Lease Purchase
It is vital to distinguish between a lease option and a lease purchase. Under a lease option, the buyer holds the choice to purchase or walk away when the lease term expires, though they typically forfeit any upfront option fee if they choose not to buy. Conversely, a lease purchase agreement often creates a binding legal obligation for the tenant to buy the property at the end of the term.
How Rent-to-Own Arrangements Work
Rent-to-own is a broad consumer term rather than a standardized financial product. Because every contract is privately negotiated between a buyer and a seller, terms can vary dramatically. Because legal and financial implications are significant, buyers should always have their agreement reviewed by an appropriately qualified real estate attorney before signing. Consulting Florida residential lease and tenancy regulations can also provide valuable context regarding state-specific tenant rights.
Why a Lease Option May Appeal to First-Time Buyers
A lease option can be an attractive strategy for specific buyers who need time rather than an immediate purchase. Potential advantages include:
Time to build savings for a down payment and closing costs.
Opportunity to improve credit scores through consistent on-time rental payments.
The ability to lock in a purchase price in a rising market.
Familiarity with a specific neighborhood before committing to permanent ownership.
However, these potential benefits depend entirely on the specific contract terms and the buyer’s financial discipline.
The Potential Risks of a Lease Option
While lease options offer flexibility, they also carry distinct risks that every first-time buyer must evaluate carefully.
Option Fees and Rent Credits
Buyers usually pay an upfront option fee, which is often non-refundable. Additionally, a portion of monthly rent payments might be designated as a rent credit toward the purchase price. However, buyers must never assume these credits will automatically satisfy lender requirements. Under current mortgage qualification standards, lenders enforce strict documentation rules regarding how option fees and rent credits are sourced and applied.
What Happens If You Cannot Qualify for a Mortgage?
A lease option does not eliminate the need for a mortgage. If the buyer cannot secure financing when the option period expires, they typically lose their option fee, accumulated rent credits, and the home itself. Being approved for a lease option by a private landlord is entirely different from meeting formal mortgage underwriting guidelines.
What If the Home Does Not Appraise at the Agreed Price?
If the agreed purchase price exceeds the home value determined by a future appraisal, securing a mortgage for the full contract amount becomes difficult. Buyers may need to bring additional cash to the closing table to cover the difference.
What First-Time Buyers Should Know About Financing
Securing a lease option is not a substitute for mortgage pre-approval. When the option period ends, the buyer must qualify for a traditional home loan based on their credit history, debt-to-income ratio, employment stability, and verified assets. Reviewing first-time homebuyer loan options early in the process helps buyers understand what lenders expect. Utilizing mortgage calculators can also clarify how future monthly obligations will look. If credit improvement is needed, exploring structured credit preparation guideeresources provides a solid foundation.
Lease Options in the 2026 Housing Market
In the 2026 housing market, affordability pressures and fluctuating inventory prompt some buyers to explore alternative purchasing structures. While 2026 first-time homebuyer housing trends indicate that traditional financing remains the primary path to ownership, lease options occasionally emerge when buyers need extra time to stabilize their financial profiles.
Questions to Ask Before Signing a Lease Option
Before entering into any rent-to-own agreement, buyers should investigate several critical questions:
What is the exact purchase price, and how was it determined?
Is the option fee refundable under any circumstances?
How much of the monthly rent is credited toward the purchase price?
Who is responsible for property taxes, insurance, and major repairs during the lease?
What specific financing milestones must be achieved before closing?
Is the agreement legally recorded to protect the buyer’s interest?
Is a Lease Option Right for You?
Deciding whether to pursue a lease option depends on your current financial readiness. If you have stable income, a clear plan to improve your credit, and need a structured timeline to finalize your savings, a lease option may be worth investigating with professional guidance. If you already meet credit and savings requirements, a traditional purchase often provides greater transparency and market flexibility.
Final Takeaway
A lease option is a complex financial and legal tool rather than a guaranteed shortcut to homeownership. Understanding contract terms, recognizing potential risks, and preparing for future mortgage qualification are essential steps for any prospective buyer. If you want to evaluate your purchasing power or explore your financing options, contact LevelMTG today to speak with an experienced mortgage professional.
Want personalized assistance? Visit our 'Contact Us' tab and leave your information with one of our experts.
About Us
A group of like-minded seasoned veterans came together to create a company with an employee-focused culture. A culture that values its members both personally and professionally and a company built on the idea that the customer comes first!
We do not share data with third parties for marketing/promotional purposes.
By submitting your phone number to Level Mortgage, you are authorizing a representative of our company to send you text messages and notifications. Message frequency may vary. Message/data rates apply. Reply STOP to unsubscribe to a message sent from us, and HELP to receive help.